Auto Insurance Bundling California: How To Build A Wise Bundle
California drivers are leaving money on the table by not bundling their insurance policies. Auto insurance bundling in California can cut your premiums by 15% to 25%, according to industry data.
We at Cappuccino Insurance Agency help drivers build smart bundles that match their actual needs. This guide walks you through the process step by step.
Understanding Auto Insurance Bundling in California
What Bundling Actually Means in California Insurance
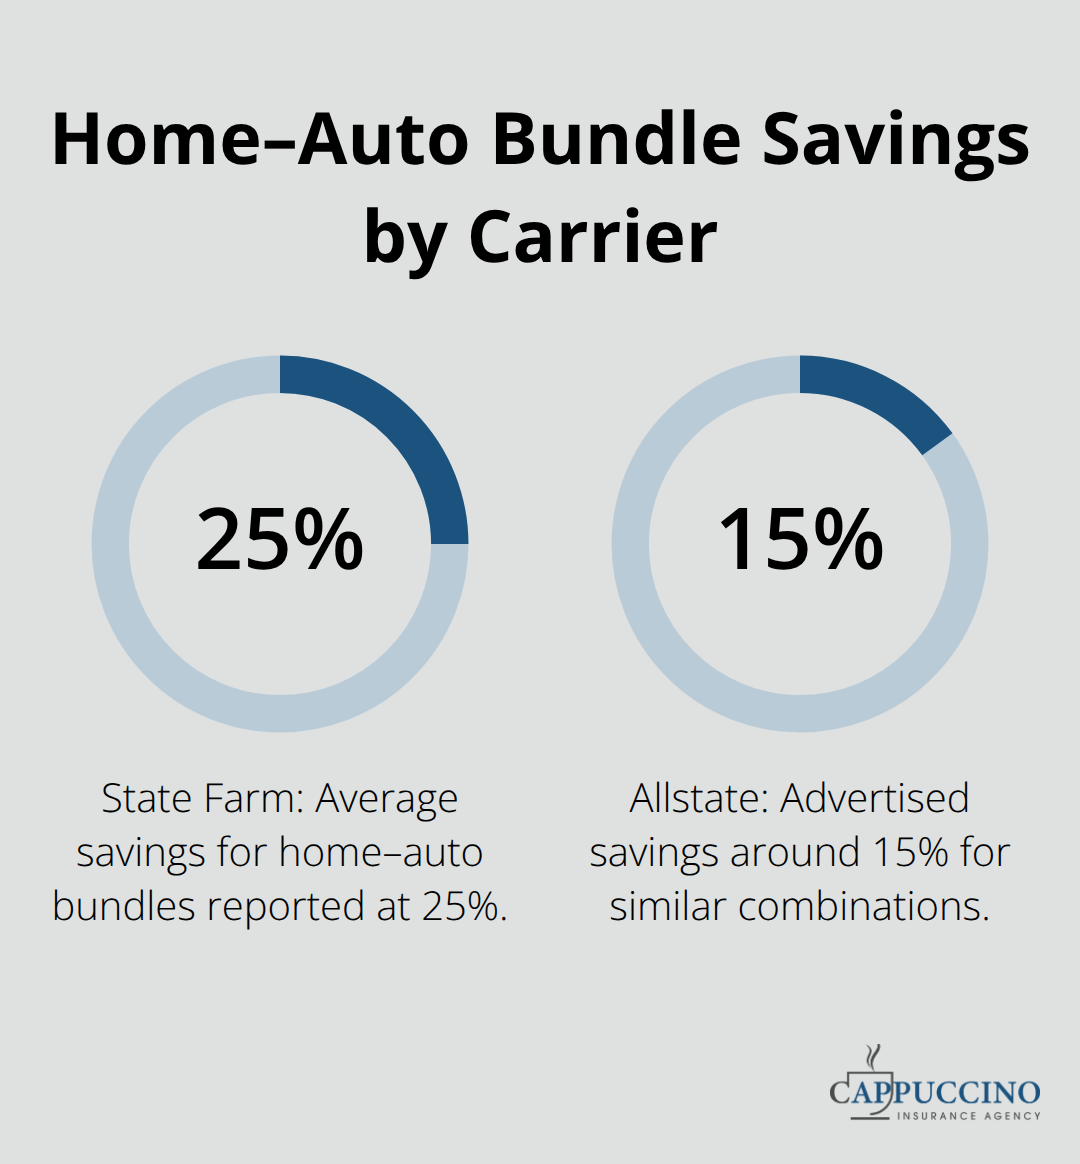
Bundling combines multiple insurance policies with one carrier or through one agency to receive a discount. California drivers typically bundle auto insurance with home insurance, but the combination extends further. Life insurance, umbrella policies, and commercial coverage all qualify for bundle discounts at most carriers. The discount varies significantly by insurer and your specific situation. State Farm reports that bundling home and auto saves customers an average of 25%, while Allstate advertises savings around 15% for similar combinations. Your actual savings depend on your risk profile, claims history, location within California, and the specific policies you combine.
Some carriers offer tiered discounts, meaning you save more when you bundle three or more policies rather than just two. This structure incentivizes adding coverage you might actually need anyway, making bundling financially smarter than shopping policies separately.
Why California’s Market Makes Bundling Valuable
California’s insurance market operates differently than most states due to Proposition 103, which limits how much insurers can raise rates based on driving record alone. This regulatory environment means carriers compete heavily on bundle discounts instead of aggressively penalizing individual drivers. California drivers pay some of the highest auto insurance rates in the nation, with average premiums around $2,300 annually for full coverage. Bundling becomes your direct path to reducing this cost without sacrificing coverage. The 15% to 25% savings translates to $345 to $575 annually on auto insurance alone, and those savings compound when you add home or life policies to the bundle. An independent agency works with multiple carriers across California, which means identifying which insurers offer the strongest bundle discounts for your specific situation rather than forcing you into one company’s standard package.
The Real Mechanics Behind Bundling Savings
Carriers profit from bundling because it increases customer lifetime value and reduces switching likelihood. When you bundle, you become statistically less likely to shop around annually, which saves the insurer significant acquisition costs. They pass a portion of these savings to you through discounts that typically range from 10% to 30% depending on how many policies you combine. Some insurers structure bundle discounts as a percentage off your total premium, while others apply separate discounts to each policy. This distinction matters because a 15% discount applied to your total bill differs from 15% off auto plus 15% off home. You need to compare the final dollar amount, not just the percentage advertised. California drivers often overlook that bundling also simplifies your life operationally-one renewal date, one payment method, one point of contact for questions or claims. This convenience factor alone motivates many people to stay bundled, which explains why carriers are willing to discount aggressively.
What Policies Qualify for Bundling
Most California insurers allow you to bundle auto with home, life, umbrella, and commercial policies. The specific combinations available depend on your carrier’s product offerings. Not every insurer offers every type of coverage, so your bundle options may vary. Some carriers specialize in auto and home bundles, while others excel at adding life or commercial policies to the mix. The more policies you consolidate with one carrier, the larger your discount typically becomes. This is where understanding your full insurance picture matters before you commit to a bundle.
Types of Insurance Policies You Can Bundle
Home and Auto: The Foundation of Smart Bundling
Home and auto bundling remains the most common combination California drivers choose, and for solid financial reasons. When you add home insurance to an existing auto policy, most carriers knock 15% to 25% off your combined premium according to industry benchmarks. The mechanics work because a homeowner with auto coverage presents lower overall risk to an insurer than separate customers. Geico and Progressive both advertise home-auto bundle savings around 15%, while regional carriers sometimes push higher discounts to compete.
The real advantage surfaces when you calculate the total dollar reduction across both policies rather than focusing on the percentage alone. A driver paying $1,800 annually for auto coverage who adds a $1,200 home policy might receive a 20% discount on the combined $3,000 total, saving $600 yearly. That same 20% applied only to the auto portion would yield just $360 in savings, making the full bundle substantially more valuable.
Expanding Your Bundle With Life Insurance
Life insurance and commercial coverage expand your bundle options further, though fewer drivers take advantage of these combinations. Adding term life insurance to your home-auto bundle typically generates an additional 5% to 10% discount on your total premium, depending on your carrier and the life coverage amount you select. The discount structure matters here because some insurers apply tiered bonuses that reward consolidation more aggressively than others.
Your life insurance needs depend on your dependents, outstanding debts, and income replacement goals. A term life policy bundled with your existing coverage costs less than purchasing it separately, making bundling the practical choice if you already need the protection.
Commercial Coverage for Business Owners
Business owners operating in California find that bundling commercial liability or property insurance with personal auto and home policies creates meaningful savings, often reaching 20% to 30% combined when three or more policy types stack together. Umbrella policies, which provide liability coverage beyond your standard limits, qualify for bundling at most carriers and cost between $150 and $300 annually for $1 million in additional coverage.
This coverage becomes especially practical if you own real estate, have significant assets, or face elevated liability exposure from business activities. Your bundle strategy should match your actual life stage and risk exposure rather than adding unnecessary policies just to chase a slightly larger discount. Understanding which combinations work for your situation sets the stage for evaluating bundle options across multiple carriers.
Strategies for Building the Right Bundle for Your Needs
Assess Your Current Coverage Gaps
Most California drivers never assess what coverage they actually own, which means they leave thousands in potential savings on the table. Start by listing every insurance policy you currently hold, including auto, home, life, umbrella, and anything tied to business activities. Write down the carrier name, policy number, coverage limits, and annual premium for each. This inventory takes thirty minutes but reveals exactly where gaps exist and which policies you’re already paying for separately.
You’ll likely discover overlapping coverage you didn’t know you had or critical protection you’re missing entirely. For example, many homeowners don’t realize their auto policy includes uninsured motorist coverage that might duplicate protection already in their home policy, or they lack adequate umbrella coverage despite holding significant assets. More than 70% of homeowners are likely underinsured by an average of roughly 20%, which underscores why assessing your actual coverage matters. Once you see your full picture, you stop guessing at what bundle makes sense and start building one based on actual needs rather than what an agent suggests.
Compare Bundle Discounts Across Multiple Carriers
After mapping your coverage, contact carriers and independent agencies to compare bundle quotes side by side. This step separates the serious bundlers from the casual ones because most people skip it entirely. Request quotes that bundle the exact same policies across at least three different carriers so you’re comparing apples to apples.
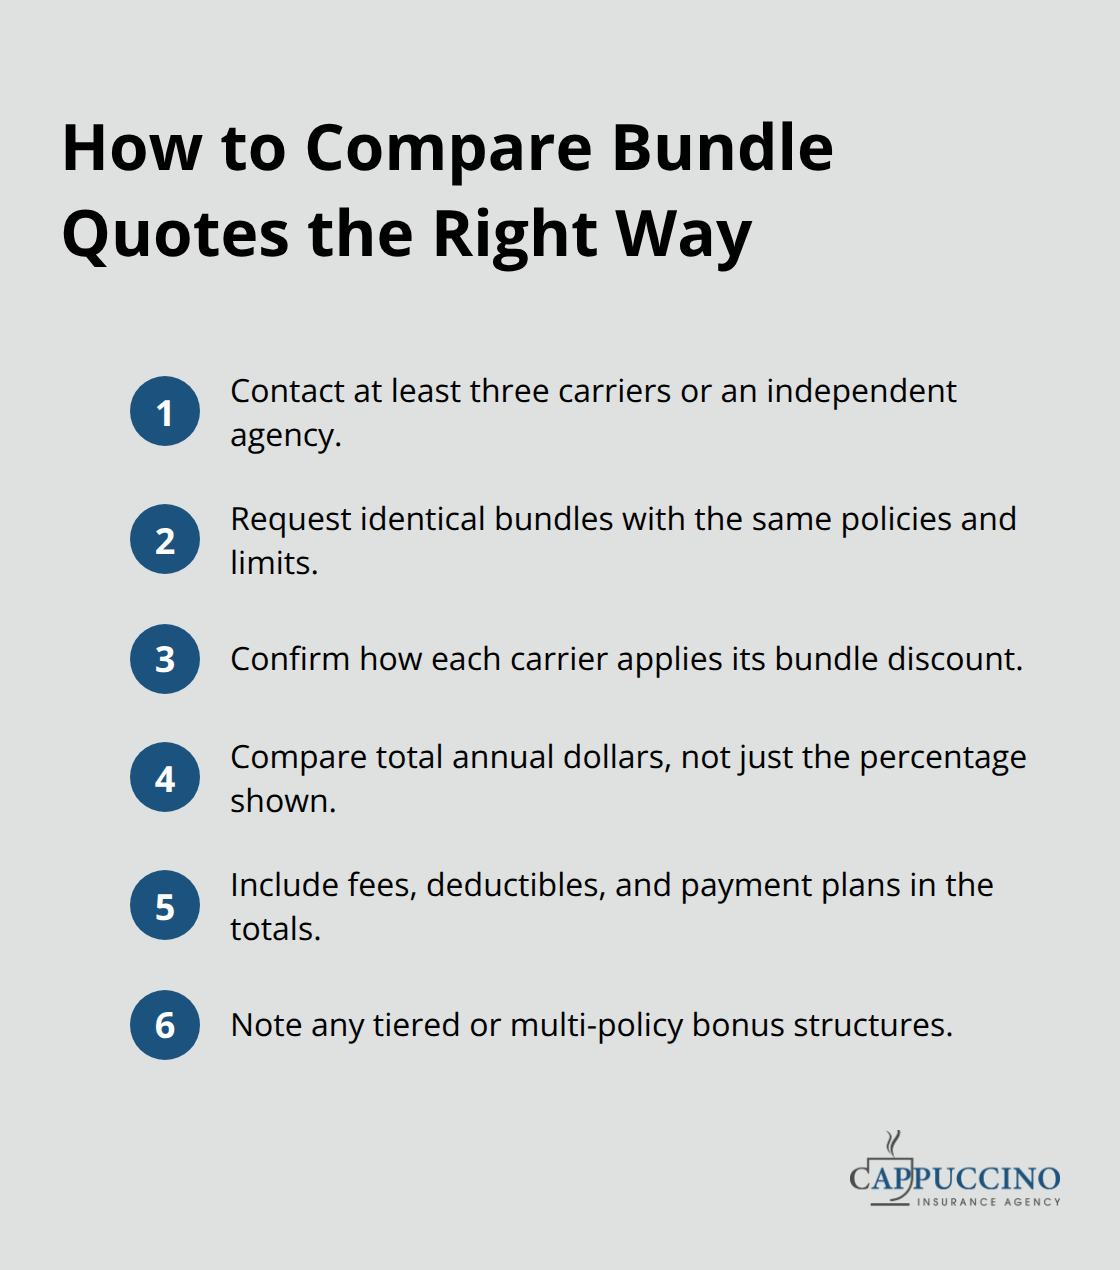
Don’t just look at the percentage discount advertised on their website, because a carrier claiming 25% off might apply that discount differently than a competitor offering 18%. Calculate the total dollar amount you’d pay annually with each bundle option. A carrier offering 20% off a $4,000 combined premium saves you $800 yearly, which beats a carrier offering 25% off a $3,600 premium that only saves $900. An independent agency works with multiple carriers across California, which means identifying which combinations deliver the strongest actual savings for your specific situation rather than steering you toward one company’s package.
Review Your Bundle Annually to Stay Protected
After you’ve selected your bundle, mark your calendar for an annual review. Your coverage needs shift as life changes, and your bundle might no longer match your situation after a year. Additionally, carriers adjust their discount structures and new competitors enter the market with better rates. Reviewing annually takes two hours and typically uncovers $200 to $400 in additional savings you missed by staying bundled with your original carrier.
Final Thoughts
Building an effective bundle requires honest assessment of your coverage needs, comparison across multiple carriers, and annual reviews to catch savings you might miss. The 15% to 25% discount range on auto insurance bundling in California translates to real money in your pocket, but only if you approach bundling strategically rather than accepting the first offer that comes your way. Your bundle should reflect your actual life stage and risk exposure, not chase discounts on policies you don’t need.
We at Cappuccino Insurance Agency work with 20+ carriers across California, which means we identify which combinations deliver the strongest actual savings for your specific situation rather than steering you toward one company’s standard package. Our team handles the comparison work for you, pulling quotes from multiple insurers and calculating the total dollar savings so you see exactly what each bundle costs annually. We also provide free coverage assessments to uncover gaps you might not see on your own, then build your bundle around those findings.
Contact us at cappuccinoinsurance.com to discuss your coverage needs and receive personalized bundle quotes from carriers competing for your business. We’ll walk you through the options, explain how each discount applies, and help you select the bundle that protects your life while reducing your annual premiums. Your annual review becomes part of our service, ensuring your bundle stays aligned with your changing needs and market conditions.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles and may contain inaccuracies.


