Difference in Conditions Wrap: Filling Gaps in California Property Coverage
California property owners face a harsh reality: standard homeowners policies leave significant gaps in coverage. Wildfire damage, high-risk properties, and specific perils often fall outside what your basic policy covers.
A Difference in Conditions wrap fills those gaps by providing additional protection where standard policies stop. At Cappuccino Insurance Agency, we’ve seen how this coverage protects California homeowners from financial disaster when the unexpected happens.
What a Difference in Conditions Wrap Actually Covers
A Difference in Conditions wrap is supplemental insurance that picks up exactly where your standard homeowners policy stops. Instead of replacing your existing coverage, it layers on top of it to address specific perils and situations your regular policy excludes or limits. The California Department of Insurance recognizes these wraps as legitimate gap-filling tools, and they’ve become essential for property owners who can’t obtain adequate protection through conventional means. The wrap covers losses from named perils that fall outside your standard policy’s scope, whether that’s wildfire damage, earthquake-related losses, or coverage for properties insurers deem too risky to underwrite traditionally.
Why Standard Policies Leave You Exposed
Standard homeowners policies in California come with built-in exclusions that surprise most property owners. Wildfire damage frequently sits in a gray zone where coverage is limited or non-existent, especially for properties in high-risk fire zones. Properties with older construction, previous claims history, or locations near brush and timber face outright rejection from major insurers.
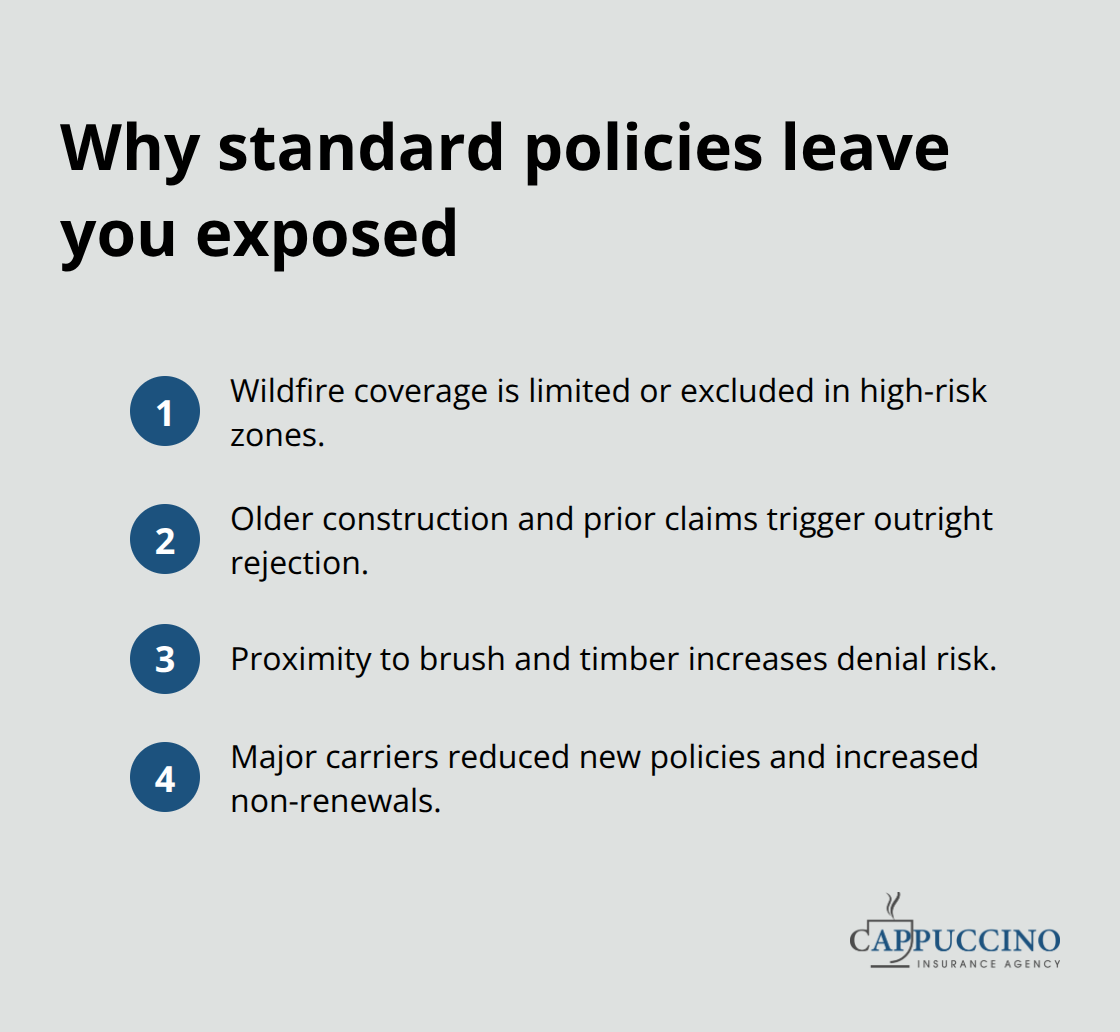
The National Association of Insurance Commissioners reported that California’s insurance market has contracted significantly, with major carriers reducing new policies and non-renewals affecting hundreds of thousands of homeowners. A Difference in Conditions wrap steps in because traditional insurers won’t, offering coverage for the exact scenarios that leave you vulnerable.
The Practical Advantage for California Homeowners
The real value of a Difference in Conditions wrap lies in its flexibility and affordability compared to other solutions. You maintain your existing coverage at its current rate while adding targeted protection through the wrap, rather than paying premium rates for a full replacement policy from a specialty insurer. This approach costs substantially less than purchasing an entirely new policy while delivering more comprehensive protection than your standard policy alone. Properties in fire-prone areas, those with claims history, or homes that simply don’t meet standard underwriting guidelines benefit most from this structure. Multiple carriers offer wrap solutions, and finding the right one for your specific situation requires expertise in matching your property’s unique risk profile to available coverage options.
Coverage Gaps in California Property Insurance
Wildfire Exclusions That Leave Homeowners Exposed
Standard homeowners policies in California contain exclusions that most property owners never discover until they file a claim. Regulatory failures have driven the chaotic collapse of California’s homeowners’ insurance market, with carriers either exiting the market entirely or dramatically restricting coverage eligibility. Wildfire damage represents the most glaring gap-many standard policies either exclude wildfire losses outright or impose such restrictive conditions that coverage becomes nearly worthless.
Properties located within a mile of known wildland areas face automatic exclusions from major carriers. Even when wildfire coverage technically exists in a policy, deductibles often reach 5% to 10% of the home’s insured value, meaning a homeowner with a $500,000 home could face a $25,000 to $50,000 deductible. This structure makes the coverage functionally useless for actual protection.
Earthquake and Older Home Rejections
Earthquake damage sits in an entirely separate category requiring additional endorsements that most California homeowners purchase at steep premiums. Older homes built before 1978 encounter blanket rejections from standard insurers due to construction methods and materials that don’t meet current seismic codes. Properties with previous claims history, regardless of severity, face non-renewal or coverage limitations that make traditional policies inadequate for meaningful protection.
High-Risk Properties and Outright Denials
High-risk properties encounter walls of rejection that go far beyond simple rate increases. A home in a fire-prone zone with a previous claim from five years ago will find virtually no coverage options through standard market insurers. Properties with wood shake roofs, those lacking defensible space around structures, or homes in areas designated as very high fire hazard severity zones get declined outright.
The California Department of Insurance data shows that properties deemed uninsurable through the standard market now number in the hundreds of thousands. Secondary perils like wind damage, hail, and water intrusion also encounter limitations or exclusions in standard policies, leaving homeowners exposed to losses that can cost tens of thousands in repairs. These gaps create a critical need for supplemental protection that addresses exactly what standard insurers refuse to cover.
How a Difference in Conditions Wrap Protects Your Property
How the Wrap Layers Over Your Existing Coverage
A Difference in Conditions wrap for California property insurance fills the specific perils your standard policy refuses to cover, and the mechanics are straightforward. The wrap sits on top of your existing homeowners policy without replacing it, meaning you keep your current coverage and rates while gaining supplemental protection for named perils your standard insurer excludes. This approach works because wrap carriers specialize in risks that traditional insurers reject outright.
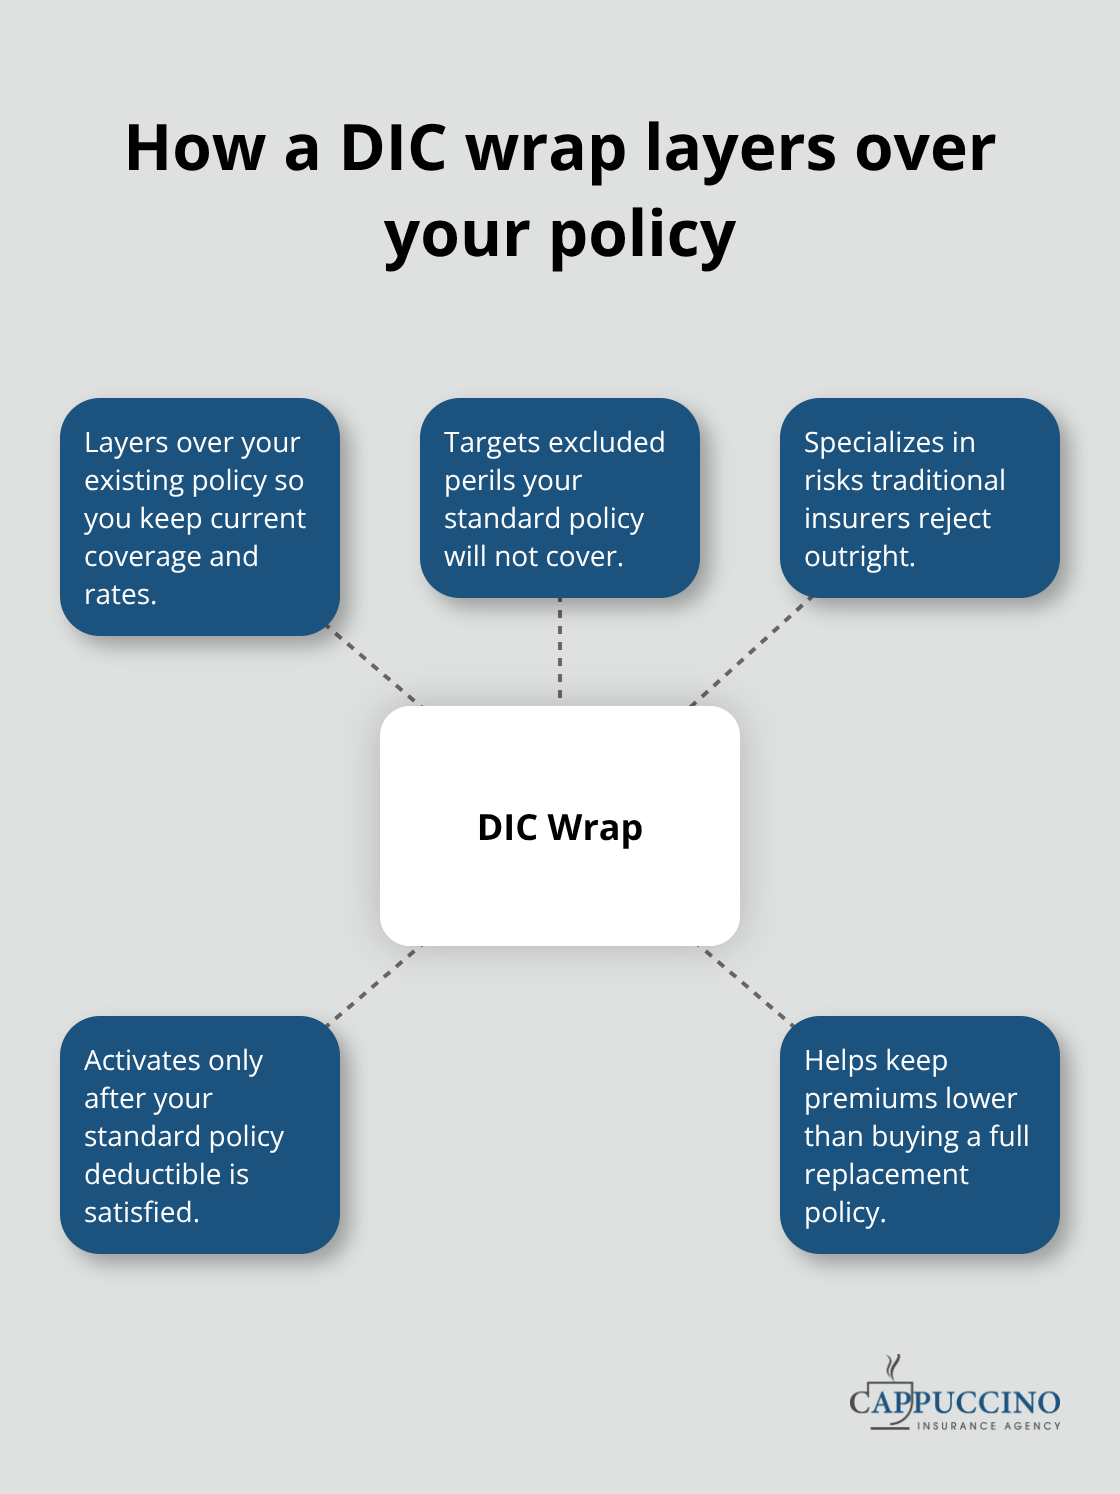
If your standard policy excludes wildfire damage or denies coverage for properties with previous claims, the wrap picks up exactly those scenarios. The coverage activates only after your standard policy’s deductible is satisfied, which keeps premiums lower than purchasing a full replacement policy from a specialty carrier.
Real Protection Where Standard Coverage Fails
Properties in fire zones with deductibles reaching 5% to 10% of home value benefit tremendously because the wrap covers losses that fall within that gap. For a $500,000 home facing a $25,000 deductible, the wrap provides real protection where standard coverage becomes functionally useless. Older homes built before 1978 that cannot obtain earthquake coverage through standard channels find wrap solutions that address seismic risk at reasonable rates. Properties with wood shake roofs, defensible space issues, or locations in very high fire hazard severity zones receive coverage through wraps when major carriers simply decline them.
Cost Advantage Over Full Replacement Policies
The cost advantage makes wraps the practical choice for California homeowners facing rejection from standard market insurers. A wrap typically costs 40% to 60% less than purchasing a full replacement policy from a specialty insurer while delivering comparable protection for the perils that matter most. The California Department of Insurance recognizes wraps as legitimate solutions for the hundreds of thousands of properties now considered uninsurable through traditional channels.
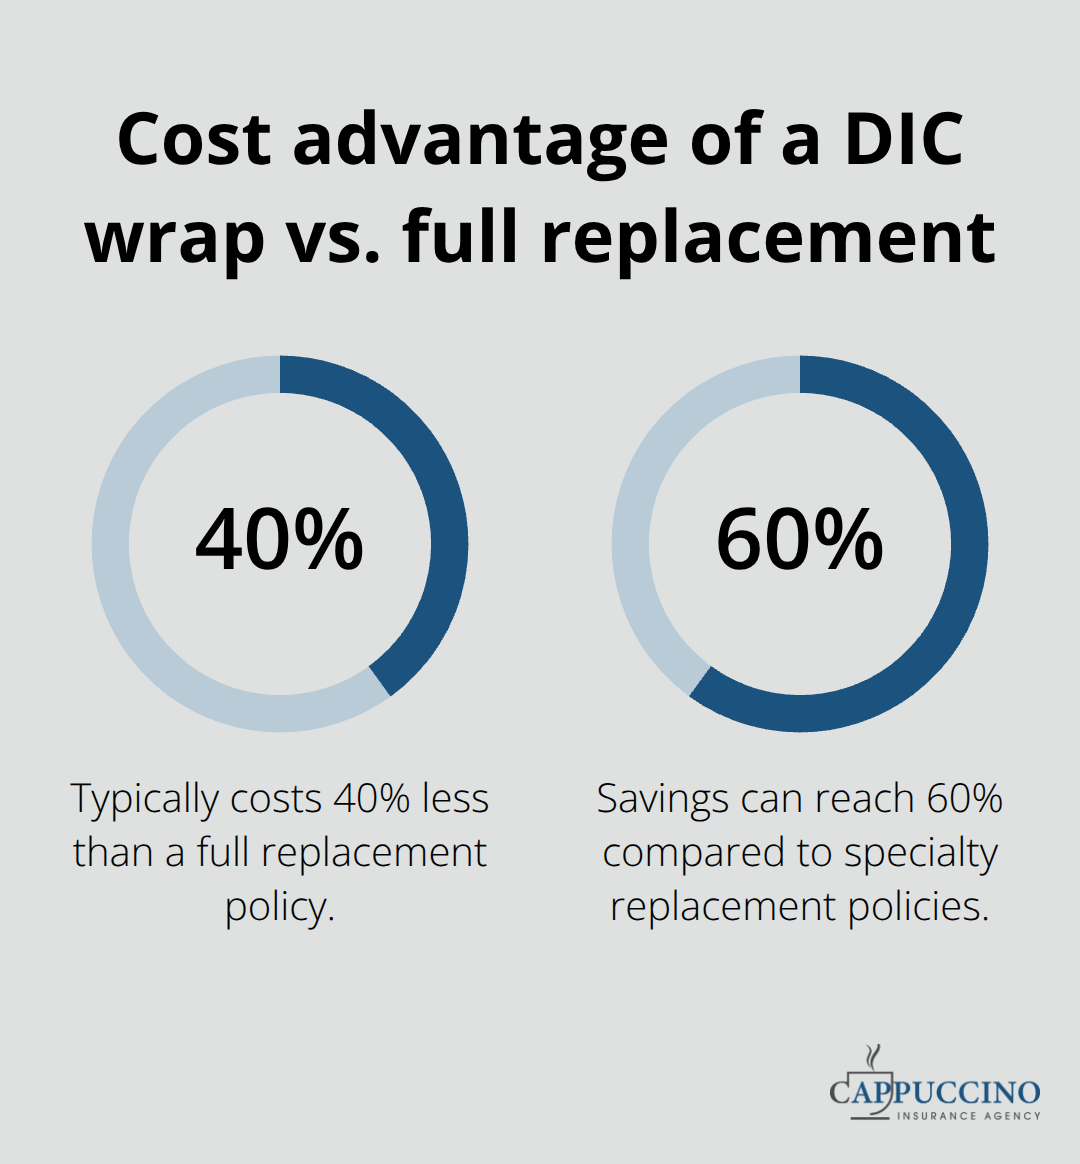
Hard-to-place properties benefit most because they have limited options, and wraps provide meaningful protection without the astronomical premiums that specialty carriers charge for full replacement policies.
Secondary Perils and Additional Coverage
Secondary perils like wind and hail damage receive coverage through wraps when standard policies exclude them, addressing the gaps that cost homeowners tens of thousands in repairs. Properties with previous claims history, regardless of severity, face non-renewal or coverage limitations that make traditional policies inadequate for meaningful protection. The wrap structure allows carriers to specialize in these exact risk profiles because one wrap solution does not fit every situation.
Final Thoughts
California property owners without a Difference in Conditions wrap face real financial exposure when standard policies exclude the perils that matter most. Wildfire damage, earthquake losses, and properties with previous claims history sit outside traditional coverage, leaving hundreds of thousands of homeowners vulnerable to catastrophic costs. Your current policy has gaps, and those gaps will cost you money when disaster strikes.
A Difference in Conditions wrap addresses the exact perils your standard policy refuses to cover while costing substantially less than full replacement policies from specialty carriers. Homes in fire zones facing 5% to 10% deductibles, older properties without earthquake coverage, and any property with previous claims history benefit most from this supplemental protection. The wrap delivers meaningful coverage where major insurers have already rejected you.
Contact Cappuccino Insurance Agency to review your current coverage and identify where a Difference in Conditions wrap could strengthen your protection. We work with multiple carriers to find solutions for hard-to-place properties and provide free assessments of your specific gaps. A no-obligation review takes minutes and could reveal exactly what your property needs to stay protected.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles and may contain inaccuracies.


